Five Things to Check Before Investing in Cement Companies
Last checked: 13 October 2026. This is a short checklist for beginners, not financial advice. The figures are examples from BUA Cement and Dangote Cement filings and news coverage, and they will change with each report.
You do not need a finance degree to ask good questions about a cement company. Five checks cover most of what matters, and each one can be done with a company’s latest report and a few minutes of arithmetic.
1. Is the profit real and growing?
Look at revenue, operating profit and profit after tax for the latest period and for the same period a year earlier. BUA Cement’s half-year revenue rose to ₦728.9 billion and its profit after tax to ₦324.9 billion, up about 79.6%. Dangote’s rose 22.7% to ₦638.5 billion. Then check the trend inside the year. BUA’s second-quarter profit after tax of about ₦148.5 billion was lower than the first quarter’s ₦176.4 billion, so one strong half does not tell the whole story. Also confirm that cash flow from operations supports the reported profit.
2. How much of each naira is left after costs?
Margins show efficiency. BUA’s operating ratio improved to 49.1% from 57.9%, and Dangote’s group EBITDA margin was 47.3%. In cement, energy and exchange-rate movements can change margins quickly, so check what management says about costs. If margins rise, ask whether it came from lower costs or only from higher prices that regulators or customers may push back on.
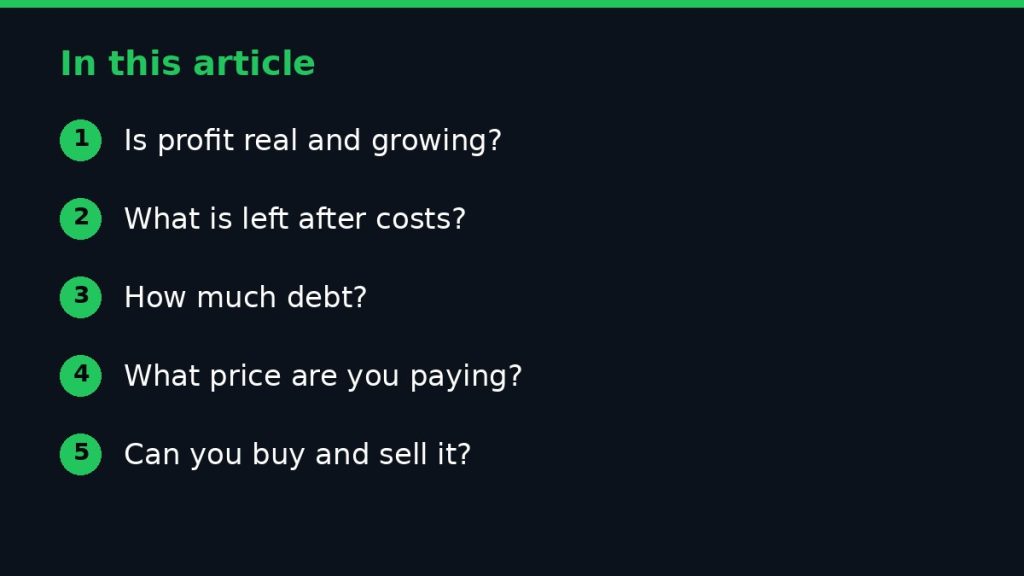
3. How much debt does it carry?
Plants are expensive, so borrowing is common. Check total borrowings, interest paid and cash on hand. BUA reported cash and short-term deposits of about ₦303.6 billion at 30 June 2026. Dangote’s finance costs fell from about ₦216.2 billion to ₦112.1 billion over the year, and Proshare said it moved to net cash. Look at how many times profit covers interest. Debt that is comfortable in good times can become heavy when construction slows or interest rates rise.
4. What price are you paying?
A great company can still be a poor investment at too high a price. Compare the share price with earnings, called the price-to-earnings ratio. Doubling half-year earnings per share as a crude annual estimate gives about 15.5 for BUA at ₦297 and about 14 for Dangote at ₦1,066.70. Also look at the dividend yield, about 3.4% and 4.2% on those prices. These measures are rough, and different data sites use different methods. Compare each company with its own history and with its peers.
5. Can you actually buy and sell it?
Liquidity and ownership matter. BUA’s free float value was reported near ₦266.6 billion against a market value of roughly ₦10 trillion, so only a small portion trades freely. That can mean wide gaps between buying and selling prices and sharp moves on modest volume. Check the bid, ask and volume on your broker’s platform, and remember that trading costs are typically 1.5% to 2.5% of the value on a purchase according to beginner guides.
A quick scorecard
For each company you study, write one line per check: profit trend, margin, debt, valuation, liquidity. Add the date. If you cannot fill a line, you are missing information, and that is a reason to read more before investing.
Do the same exercise for a second company so you can compare. Reading two reports side by side teaches you more in an hour than reading one report for a week, and it shows which numbers are normal for the industry.
Other points worth a glance
- Regulatory news, such as the FCCPC inquiry into cement pricing.
- Capacity plans and how they are being funded.
- Whether the dividend is covered by earnings.
- The exchange rate and energy costs, which feed through to margins.
Common mistakes
- Buying after a big price jump without checking the numbers.
- Trusting a single data site. One site showed a BUA dividend of ₦312 when the company announced ₦10.
- Comparing share prices instead of valuations.
- Ignoring how much you can afford to lose.
What we could not confirm
- Total borrowings for BUA Cement, which you should read in its balance sheet.
- Any company’s future results or dividends.
- Exact valuation ratios, since methods vary.
Frequently asked questions
Which check matters most? There is no single one. Profit quality, debt and price together give a fuller picture.
How often should I repeat the checks? After each quarterly report.
Can I skip the checks if an analyst recommends it? Analysts often disagree, with targets for BUA ranging from about ₦150 to above ₦400, so do your own reading.
Key takeaways
Check profit and its trend, margins, debt, valuation and liquidity. Verify numbers against company filings, record what you find and invest only money you can leave alone for years.
Be suspicious when a dividend yield appears unusually high. A collapsing share price can make the yield look impressive even when the underlying business is deteriorating. Check debt levels, declining earnings, cash reserves, and management guidance before drawing conclusions.
Sources checked
- Nairametrics, BUA Cement and Dangote Cement H1 2026 reports
- Africanfinancials and Arbiterz BUA Cement results summaries
- Proshare, Dangote Cement H1 2026 results analysis
- StockAnalysis, Investing.com and Simply Wall St quote pages
- NairaCompare beginner’s guide to buying shares on the NGX
Educational content only — not financial advice. Income and savings results vary and are never guaranteed. How we write
Enjoyed this story?
Get the best stories delivered weekly.